View:
October 02, 2026
Preview: Due October 16 - U.S. September Industrial Production - Rebound from a weak August

October 2, 2026 5:32 PM UTC
We expect a strong 1.0% increase in September industrial production after flat August with manufacturing up by 0.6% after a 0.3% August decline. This would restore a positive trend after a weak month.
FX Weekly Strategy: Asia, Oct 5-8
October 2, 2026 3:51 PM UTC
US yields put in a potential n/t weekly top as data plays to Fed lack of urgency
Euro still weighed on crosses until/unless politicians manage a convincing response; mkt tends to escalate into a forced crisis reaction
Fiscal saints may come back onto the agenda, so long as US bonds and risk steady at

Preview: Due October 5 - U.S. September ISM Services - Maintaining a fairly steady picture
October 2, 2026 3:12 PM UTC
While the S and P services PMI has accelerated sharply though Q3 after being quite subdued in Q1 and Q2, we expect the ISM services index to maintain a fairly steady profile that has been seen in the year to date, correcting lower to 55.0 from August’s 55.4, which was up from 54.1 in July.
Preview: Due October 20 - U.S. September Housing Starts and Permits - Mixed but on balance negative
October 2, 2026 2:58 PM UTC
We expect September housing starts to increase by 1.2% to 1290k after two straight declines while permits fall by 2.6% to 1370k, a second straight fall. On balance this would imply a slowing housing market.
U.S. September Employment - Trend looking subdued again
October 2, 2026 1:12 PM UTC
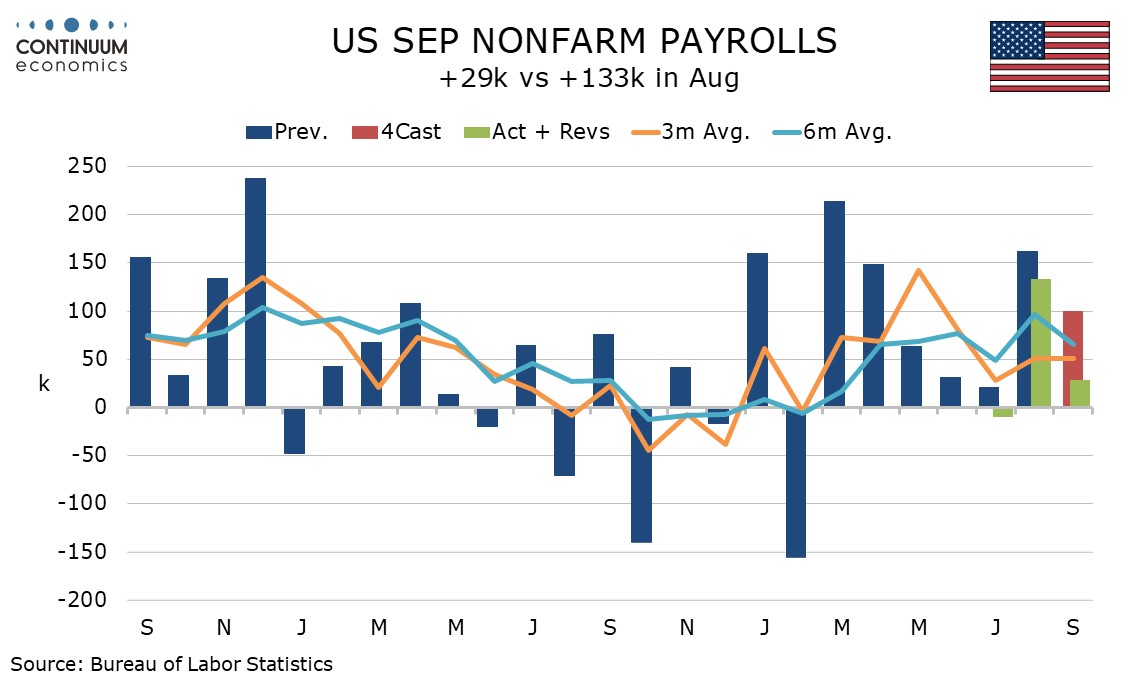
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
U.S. September Employment - Trend looking subdued again
October 2, 2026 1:12 PM UTC
September’s non-farm payroll at 23k, 46k private, with negative back revisions, is weaker than expected and returns the picture to near flat after the stronger August. Average hourly earnings are slowing, up only 0.1%, though the rise in unemployment to 4.2% from 4.1% is on a rise in the labor for
EUR/USD, USD/JPY flows - Payrolls dulls urgency, 157 attracts even if euro still reluctant to bounce
October 2, 2026 12:37 PM UTC
Payrolls report largely softer than expected across the board
Tends to reinforce lack of urgency from some Fed members
USD/JPY reset to 157 expiry, euro more reluctant to bounce given France issues
EZ Inflation Jumps - Still Energy Driven
October 2, 2026 10:34 AM UTC
Although headline inflation for September was higher than expected at 3.8%, when consensus forecast 3.2%, the narrative does not change. This is still an energy driven increase in inflation. The breakdown of overall inflation into major components showed that energy was the largest contributor to th
EZ Inflation Jumps - Still Energy Driven
October 2, 2026 10:33 AM UTC
Although headline inflation for September was higher than expected at 3.8%, when consensus forecast 3.2%, the narrative does not change. This is still an energy driven increase in inflation. The breakdown of overall inflation into major components showed that energy was the largest contributor to th
Europe Summary and Highlights 2 Oct
October 2, 2026 10:05 AM UTC
Dollar breather into payrolls, euro still weighed on crosses
OAT-bund still wider, if on underperformance, political development become key next few days
CHF still profit-taking/short covering with switch in focus from carry to risk avoidance
Japan CPI comes in high, EZ follows national prints; payro
EUR/CHF flows: Spread still going, cross back to recent lows; w/e key window?
October 2, 2026 8:28 AM UTC
OAT-bund spread still widening, if through OAT lagging rather than further selling; has all but met 150bp now
Weekend could be key for politicians to try and stem the snowball effect; failure to convince could just attract more pressure
EUR/CHF has been one pure expression of the regime shift this wee